ATP Player Pension Plan 2026: Eligibility, Contributions & Payouts
A source-first guide to the ATP Tour player pension plan, including Years of Service, contribution tiers, vesting, payout illustrations and the limits of public information.
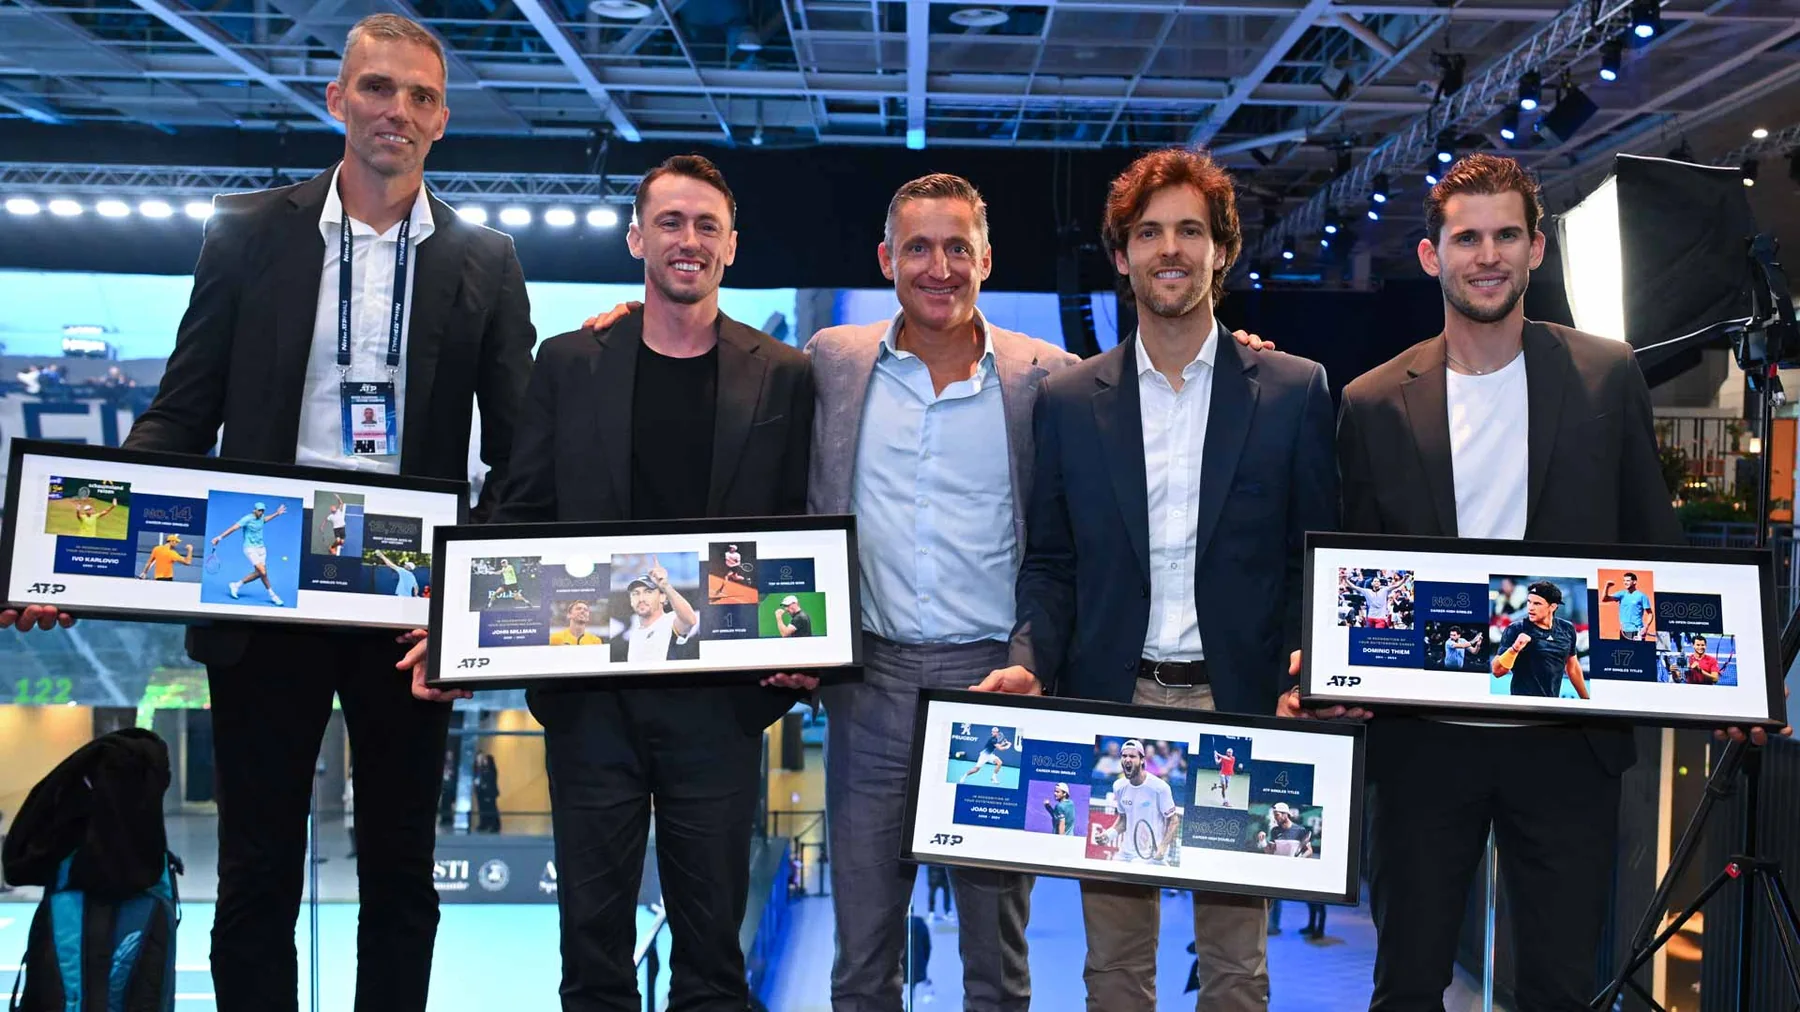
The ATP Player Pension Plan is a retirement benefit for eligible ATP Tour player members—not prize money, a salary or Denmark’s similarly named public pension. In 2026, ATP says as many as 300 players can earn service through defined ranking and participation criteria, with different contribution levels for Tier 1 and Tier 2.
This guide follows ATP’s 2026 announcement and current public rules, then draws a firm line around what those sources cannot tell us. It explains Years of Service, vesting and the Tour’s payout illustration without turning an example into a personal promise. Amounts can change, investment results vary, and a player’s official plan record remains controlling.
Quick answer: A qualifying season can earn one Year of Service. ATP publicly says three years can unlock partial benefits and five years are needed for full benefits. The 2025 annual contributions reported in 2026 were $129,550 for Tier 1 and $20,000 for Tier 2; those are plan contributions, not guaranteed 2026 payouts.
What the ATP Player Pension Plan Is in 2026
The ATP Player Pension Plan is a retirement benefit for qualifying men’s professional tennis players. It is not a wage for being ranked, a prize-money payment or a cash bonus delivered after a tournament. A player first has to meet the plan’s season-specific participation and ranking criteria, earn a Year of Service and receive the contribution attached to his tier. Service accumulated across seasons can then lead to benefits later in life.
ATP says the programme was formally established in 1990 and can now support up to 300 players in a season. That headline needs one important qualifier: “up to 300” describes the expanded annual group that can meet the contribution criteria, not every player listed in the PIF ATP Rankings. An athlete can have a public profile in the ATP player directory without a fan being able to infer his pension status from it.
A deferred Tour benefit, not match earnings
The cleanest way to understand the plan is to keep five stages separate:
- Season qualification: the player satisfies the applicable membership, participation and ranking conditions.
- Service credit: that qualifying season becomes a Year of Service.
- Contribution: the plan credits the amount associated with Tier 1 or Tier 2 for that season.
- Vesting: enough Years of Service make some or all of the benefit available under the plan.
- Distribution: eligible money is paid under the later-life rules, rather than treated as current on-court earnings.
This sequence matters because the most searchable numbers sit at different stages. A published annual contribution is not the same thing as a player’s account balance, and neither is the same as a future monthly payment.
What “2026” means here
ATP’s current public explanation was issued on 2 April 2026. The 2026 Rulebook places retirement programmes within ATP’s “Platinum Benefits,” while noting that the detailed benefit terms live in PlayerZone. So this guide explains what ATP has publicly confirmed as of 2026; it does not replace the governing plan document or an individual benefit statement.
How a Player Earns a Year of Service
A Year of Service is credit for one season in which a player meets the pension plan’s defined conditions. ATP’s 2026 explanation says those conditions include both participation and ranking. Reaching a ranking once, appearing in one draw or holding an ATP membership card does not, by itself, prove that a player earned pension service for that year.
The publicly confirmed ranking groups
Tier 1 singles
Top 150 singles players who also satisfy the applicable participation and plan conditions can qualify for a full contribution.
Tier 1 doubles
Top 50 doubles players form the doubles route into the full-contribution group. This is a player ranking, not a list of 50 teams.
Tier 2 singles
A further 100 singles players can receive a partial contribution, subject to the plan’s full criteria.
Those bands explain the 200 full-contribution places and 100 partial-contribution places in ATP’s announcement. They do not reveal every administrative detail. ATP’s public article does not specify the precise pension ranking date, every qualifying tournament count, treatment of ties or every exception. Those are matters for the official plan documentation, not assumptions built from a live rankings screen.
Membership and good standing still matter
The 2026 Rulebook gives useful context without replacing the plan. Group 1 membership is open to players who are Top 250 in singles or Top 50 in doubles at the 2025 official year-end or at some point in 2026, including via protected ranking, provided they pay dues and satisfy ATP’s other criteria. It also treats retirement programmes as Platinum Benefits and attaches good-standing conditions.
That creates an important distinction: the membership range is not the complete pension formula. For example, Top 250 singles is the published Group 1 membership boundary, while Top 150 singles is the full-contribution pension band. The remaining questions—participation, the ranking snapshot used by the plan and any exceptions—must still be resolved under the plan terms.
Fans can use completed ATP results to follow what a player did on court, but those results cannot certify a Year of Service. The definitive record belongs to ATP and the plan administrator. For a player or adviser, the practical move is to confirm service credit in PlayerZone after the season rather than estimate it from a public ranking.
Tier 1 vs Tier 2 Contributions: What the Numbers Mean
The latest ATP figures put the two tiers far apart: $129,550 for a Tier 1 qualifier and $20,000 for a Tier 2 qualifier. But the date label is essential. Those are the contribution levels for 2025, reported in ATP’s April 2026 announcement. ATP did not describe them as final 2026 contribution amounts.
| Contribution year | Tier 1 | Tier 2 | ATP-reported annual cohort |
|---|---|---|---|
| 2024 | $121,500 | $20,000 | 200 Tier 1 + 100 Tier 2 |
| 2025 | $129,550 | $20,000 | Up to 200 Tier 1 + 100 Tier 2 |
| 2026 | Not confirmed in the opened public ATP sources | Not confirmed in the opened public ATP sources | Plan remains expanded to as many as 300 qualifiers |
A contribution is not take-home pay
The word contribution does the heavy lifting. It is money credited within the retirement-plan structure for a qualifying season, not a check that replaces what a player earns in matches. ATP’s own compensation reporting separates on-site prize money, performance bonus pools and retirement-plan contributions. A fan browsing the ATP tournament calendar should therefore not add $129,550 to every Top 150 player’s visible prize-money line as if it were another event purse.
Nor is the contribution the same as a later payout. What eventually becomes payable depends on the player’s Years of Service, vesting status, credited contributions, plan terms and investment experience. The annual number tells us what went into the plan for that tier in that year; it does not tell us what arrived in a bank account or what a future monthly benefit must be.
Why the year-by-year comparison matters
Tier 1 rose by $8,050 from 2024 to 2025, while the published Tier 2 amount remained $20,000. Earlier, ATP used a different structure: 165 players qualified for a $113,600 contribution in 2023. The sensible editorial conclusion is not that contributions always rise, but that plan funding and design can change. Until ATP publishes a 2026 per-player figure, carrying the 2025 amount forward would be an unsupported forecast.
Where the Pension Money Comes From and How It Can Grow
ATP says the majority of the plan’s funding is generated by Tour data revenue, including the commercial value of live scores and match statistics. Tennis Data Innovations (TDI), established in 2021 under the OneVision strategy, manages that central data asset. ATP says the proceeds are shared equally between players and tournaments and helped total player pension contributions reach approximately $28 million in 2025.
How a live score becomes part of the Tour economy
Every point has an operational trail. The 2026 Rulebook requires tournaments to maintain networks that support official live scoring and help ATP produce and host match data. That information can then power score products, statistics and licensed services. When a fan checks today’s ATP scores, the public-facing number is the visible end of a larger data operation.
This does not mean every score-page view creates a fixed pension payment. It means the official dataset has commercial value at Tour level, and ATP says most plan funding currently comes from that revenue stream. It is also important not to merge data revenue with Masters 1000 profit sharing. ATP’s own Q&A says data revenue is excluded from the tournament profit-sharing calculation because TDI manages and distributes it separately; including it again would count the player benefit twice.
Investment performance can help—but is not a promise
After contributions enter the plan, investment results matter. ATP reported recent annualised returns averaging 15.6% and said that performance supported higher payments to current recipients. The public article does not define the exact measurement window, asset allocation or an individual player’s return, so that percentage should not be plugged into a personal compound-growth calculator.
The history itself warns against a straight-line forecast. ATP reported roughly $28 million for 2022, about $19 million for 2023 in its compensation summary, $26.3 million for 2024 and approximately $28 million for 2025. Different commercial outcomes and plan decisions can move annual funding in either direction. The sound takeaway is that data monetisation and investment performance have strengthened the plan—not that either produces a guaranteed annual return or contribution.
Vesting, Age 50 and the ATP Payout Illustration
Vesting answers a different question from annual qualification: has the player accumulated enough credited service to keep a right to benefits under the plan? ATP’s current public summary sets the first threshold at three Years of Service for partial benefits and the full-benefit threshold at five Years of Service. A player with one strong qualifying season may receive a contribution, but he has not yet met either published vesting milestone.
Step 1
Qualifying season
Earn a Year of Service and the applicable annual contribution.
3 years
Partial vesting
ATP says the three-year component, introduced in 2018, can make partial benefits available.
5 years
Full benefits
Five Years of Service are required to unlock full benefits under the public summary.
Age 50
Distribution stage
ATP describes eligible funds being paid over a 20-year period beginning at 50.
The milestones can be reached across a career; the Years of Service do not need to be described as consecutive in ATP’s public article. Still, that does not tell a reader the percentage attached to partial vesting or an individual player’s precise vested balance. Those answers belong to the plan record.
How to read ATP’s $1.2 million example
ATP offers a deliberately simple 10-year illustration. It assumes a player qualifies for Tier 1 in every one of those seasons at “current levels” of roughly $120,000 a year. Ten such credits produce approximately $1.2 million before the article discusses later monthly income. That is a model career, not the biography of a real player: it assumes no Tier 2 years, missed qualification or future change in annual contributions.
ATP then says that from age 50 the example could produce an estimated $20,000–$24,000 per month for 20 years. The words could and estimated are crucial. The figure depends on investment performance, the governing plan provisions and the assumptions behind the illustration. ATP’s prior public example, issued in January 2025, put a five-service-year Tier 1 case at $12,000–$15,000 monthly. The change is another reason not to treat a press-release illustration as a fixed benefit table.
What Is Confirmed—and What Players Must Check Privately
Public ATP sources are strong enough to explain the plan’s architecture, but not to calculate a named player’s pension. ATP directs readers to the official plan documentation for the applicable terms, while the 2026 Rulebook says the retirement-programme details are discussed in PlayerZone. That is the correct dividing line between a fan explainer and an individual benefit statement.
| Safe to say from public ATP sources | Must be checked in the current plan record |
|---|---|
| The annual programme can cover up to 300 qualifying players. | Whether a particular player earned service in a particular year. |
| ATP reported 2025 Tier 1 and Tier 2 contributions of $129,550 and $20,000. | The player's credited balance, vested percentage and investment allocation. |
| Three Years of Service can unlock partial benefits; five are needed for full benefits. | The partial-vesting fraction, exceptions or restoration of eligibility. |
| ATP illustrates distributions from age 50 over 20 years. | Payment elections, taxes, beneficiaries, survivor terms and the actual monthly amount. |
Why a public rankings calculator cannot work
A rankings file shows a sporting position; it does not show verified participation under the pension rules, good-standing status, service already credited, vesting, investment results or private elections. Likewise, this week’s ATP schedule can tell a fan where someone may compete, but it is not a benefits ledger. Any calculator using only ranking and seasons played would have to invent missing inputs.
What a player should verify
- the official Year-of-Service record for every claimed season;
- the tier and contribution actually credited for each year;
- current vesting status and the effect of any eligibility issue;
- the latest plan terms governing distribution, beneficiaries and taxes; and
- a current personal projection, clearly separated from any press-release example.
This caution is not merely legal fine print. Rulebook §1.22 says ATP may introduce, change or withdraw benefits and alter eligibility criteria. A date-stamped public guide can explain the 2026 position; only the current official record can answer a player’s personal financial question.
ATP Tennis Pension vs Denmark’s ATP Livslang Pension
“ATP pension” can mean two separate systems. In tennis, it is the ATP Tour retirement programme for player members who satisfy the plan’s season-specific ranking, participation and other conditions. In Denmark, ATP Livslang Pension is a collective labour-market pension serving almost all Danish people. A player does not enter the Danish system simply by playing a tournament there, and a Danish worker’s pension is not calculated from a tennis ranking.
Side-by-side identity check
| Question | ATP Tour player pension | Denmark’s ATP Livslang Pension |
|---|---|---|
| Who is it for? | Qualifying ATP Tour player members. | Almost all Danish people covered by the labour-market scheme. |
| How is participation described? | Defined ranking and participation criteria can produce a Year of Service. | Members/employees and employers or the state make recurring contributions; the normal employee-employer split is one-third and two-thirds. |
| When and how long? | ATP’s public illustration begins at 50 and spreads distributions over 20 years, subject to the plan. | From Danish state retirement age, which depends on birth date, with a guaranteed lifelong benefit. |
| Where is the record? | ATP Tour plan documents and the player’s private PlayerZone information. | ATP.dk and the official Life in Denmark service. |
Which official page should you use?
If the question contains “Tier 1”, “Tier 2”, “ranking”, “Year of Service” or a playing career, use ATP Tour player resources. If it contains “MitID”, “NemKonto”, a Danish payslip or state retirement age, use the Danish public-service pages. Life in Denmark says a resident’s benefit is normally paid automatically to NemKonto at retirement age; that administrative rule says nothing about a tennis player’s Tour account.
The numbers must also remain separate. A Tour contribution is not a Danish wage deduction, and the Tour’s age-50 example is not Denmark’s retirement age. Browse our ATP tennis explainers for more sport-specific definitions. For an individual benefit question in either programme, check the current record with the correct administrator instead of transferring rules across the shared acronym.
The practical bottom line for 2026: The ATP Player Pension Plan rewards sustained participation rather than one spectacular tournament. A player first has to meet the season’s ranking and participation tests, then accumulate enough Years of Service to vest. The public record supports that framework and the latest reported tier amounts, but it does not expose a named player’s credited balance, elections, tax treatment or exact future income.
For fans, the safest shorthand is: qualification earns service, ATP credits a contribution, vesting creates eligibility, and the plan terms govern distributions later. For a player or adviser, the next step is not a public rankings calculator; it is the current plan document and private PlayerZone record. And if the question is about Danish work or NemKonto, use ATP.dk—the identical acronym belongs to a different pension entirely.
About the author
ATP Schedule Editorial Team
The ATP Schedule editorial team turns match times, scores, tournament information and verified tennis news into clear answers fans can use quickly.
View all articles by this author →Fan discussion
Comments
Sign in with Google to comment. Keep the discussion helpful and tennis-focused. New comments are reviewed before they appear.
Loading comments…